Rates moved 10 basis points in a year. Warren's monthly payment moved $469.
The 30 year fixed averaged 6.66 percent on August 27 against 6.56 a year ago. Warren's median payment rose $469 a month, and price produced $407 of it.
This story updates the market tape, the running file that carries the current status.
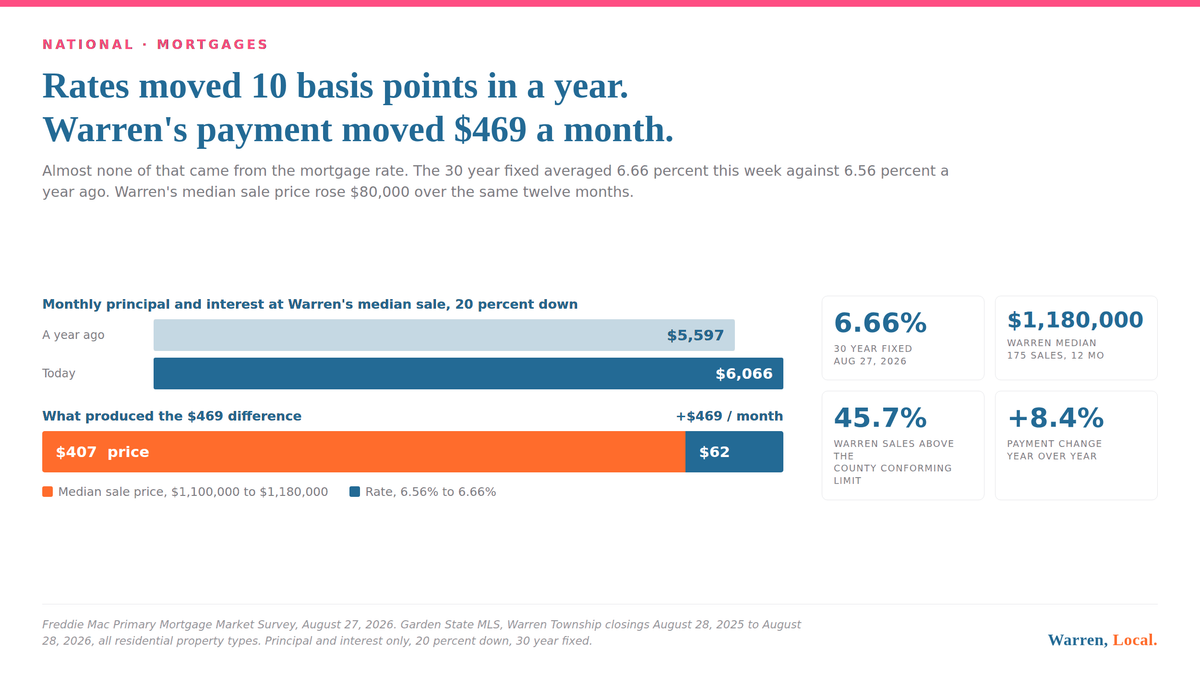
Freddie Mac put the 30 year fixed at 6.66 percent on August 27, 2026, one basis point above last week and ten basis points above the 6.56 percent it averaged a year ago. That ten basis point move is worth $62 a month on a Warren purchase. Over the same twelve months Warren Township's median sale price rose from $1,100,000 to $1,180,000, and that $80,000 is worth $407 a month. Monthly principal and interest at the median, with 20 percent down on a 30 year fixed, went from $5,597 to $6,066. Price produced 87 percent of the increase.
Most weeks the mortgage rate is the number that moves and the local price is the number that sits still. In Warren over the last twelve months it has been the other way around. The rate is almost exactly where it was last August. The price is not.
What Freddie Mac reported this week
The Primary Mortgage Market Survey released Thursday, August 27, 2026 put the 30 year fixed at 6.66 percent and the 15 year fixed at 5.98 percent. Sam Khater, Freddie Mac's chief economist, said in the release that "mortgage rates changed little this week averaging 6.66 percent" and that "the economy remains resilient, demonstrated by steady consumer spending and rising household incomes."
| Survey average | This week | Last week | A year ago |
|---|---|---|---|
| 30 year fixed | 6.66% | 6.65% | 6.56% |
| 15 year fixed | 5.98% | 5.95% | 5.69% |
The 15 year rate has moved more than the 30 year has, up 29 basis points against ten. Both are small numbers next to what happened to Warren prices.
What it costs at Warren's median
Here is the same purchase priced twice, a year apart. Both rows use 20 percent down, a 30 year fixed at the survey average of that week, and principal and interest only. Taxes, insurance and any association fee are on top of these figures, and in Warren the tax line alone is substantial.
| Window | Median sale price | Loan at 20% down | Survey rate | Monthly P and I |
|---|---|---|---|---|
| August 2024 to August 2025 | $1,100,000 | $880,000 | 6.56% | $5,597 |
| August 2025 to August 2026 | $1,180,000 | $944,000 | 6.66% | $6,066 |
| Change | +$80,000 | +$64,000 | +10 bp | +$469 |
That is $469 more a month, or $5,628 more a year, for the same position in the Warren market. The increase is 8.4 percent. The median price rose 7.3 percent over the same period, so the payment rose slightly faster than the price, and the rate is the reason for the gap.
Splitting the $469
You can separate the two causes by holding one still. Price the current $1,180,000 median at last year's 6.56 percent rate and the payment is $6,004. Compared against last year's $5,597, that is $407 attributable to price alone. Adding back the ten basis points takes it from $6,004 to $6,066, which is $62 attributable to the rate.
| Source of the increase | Per month | Share |
|---|---|---|
| Median price, $1,100,000 to $1,180,000 | $407 | 86.8% |
| Rate, 6.56% to 6.66% | $62 | 13.2% |
| Total | $469 | 100% |
One way to feel the size of that: on today's $944,000 loan, it would take the 30 year fixed falling from 6.66 percent all the way to 6.00 percent, a 66 basis point drop, to hand back the $407 a month that the price increase took. Rate relief of the size markets usually talk about, 15 or 25 basis points, does not come close in a market where the median moved $80,000.
| Rate on a $944,000 loan | Monthly P and I | Against today |
|---|---|---|
| 6.00% | $5,660 | -$407 |
| 6.25% | $5,812 | -$254 |
| 6.50% | $5,967 | -$100 |
| 6.66% (this week) | $6,066 | 0 |
| 7.00% | $6,280 | +$214 |
| 7.25% | $6,440 | +$373 |
The survey does not describe half of this market
Freddie Mac's survey tracks conforming, conventional, first lien purchase loans. That is the reason to be careful applying it here. FHFA's 2026 one unit conforming limit for Somerset County is $1,209,750, and 80 of Warren's last 175 closings, or 45.7 percent, sold above that figure. Forty of them, 22.9 percent, sold above $1,512,188, the price at which even a full 20 percent down payment still leaves a loan larger than the county limit. Those buyers price against jumbo terms, which are set by individual lenders and are not in this survey at all. The full breakdown is in where jumbo actually starts in Warren.
The $944,000 loan used throughout this post does conform in Somerset County. It is the purchases above roughly $1.5 million where the survey stops describing what a Warren buyer is actually quoted.
Principal and interest only, 30 year fixed, 20 percent down, no points, no mortgage insurance, no taxes, no insurance, no association fee. Rates are the Freddie Mac weekly survey averages for the stated week and are national averages, not quotes. Your own rate depends on credit, loan size, property type and lender. Warren prices are the median closed sale price for all residential property types in Garden State MLS over the stated twelve month window, with sales under $200,000 excluded as likely non arms length.
These figures cover every residential property type in the MLS, including townhouses and condominiums, not detached houses alone. Attached product sells below detached in Warren, so a detached only median would run higher, and so would every payment computed from it.
What I could not verify
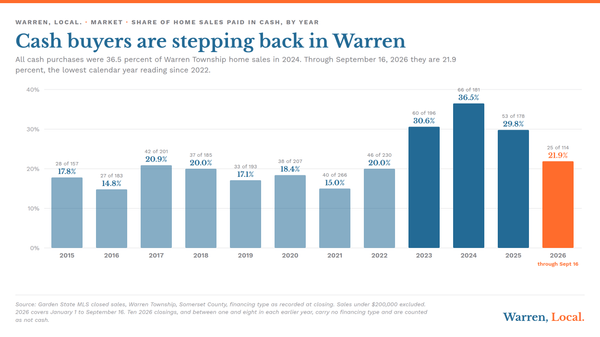
Freddie Mac does not publish a jumbo series in this survey, so there is no primary source here for what a Warren buyer at $1.8 million was quoted this week or last August. Everything above the conforming line in this post is described, not priced. I also cannot verify how the buyers in those 175 sales actually financed them. The Garden State MLS record does not carry loan amounts or down payments, so the 20 percent down assumption is a convention for comparison, not an observation. Warren's buyer pool skews toward larger down payments and cash, which is one reason a rate move that reprices an entry level market barely registers here.
I asked nothing of anyone for this post that went unanswered. Both the rate and the price come from published records.
Author's opinion
The weekly rate headline gets more attention than it earns in a market like this one. If you are buying in Warren, the rate is the smaller of the two numbers that determine your payment, and it is the one you can change later. The price you agree to is fixed for as long as you own the house. That is an argument for spending your attention on the purchase price and the house itself, not for any view about where rates go next, which I do not have and will not offer. Related reading: the Warren market page and the rate math post from August 19.
Rates in this post are the published weekly averages as of August 27, 2026 and change weekly. Check the current survey before doing your own math.
- Freddie Mac, Primary Mortgage Market Survey, August 27, 2026. https://www.freddiemac.com/pmms
- Freddie Mac, Mortgage Rates Hold Steady, news release, August 27, 2026, with the Sam Khater quotation and the year ago averages. https://freddiemac.gcs-web.com/news-releases/news-release-details/mortgage-rates-hold-steady-9
- Federal Housing Finance Agency, 2026 conforming loan limit values, Somerset County one unit limit $1,209,750. https://www.fhfa.gov/data/conforming-loan-limit
- Garden State MLS, Warren Township closed sales, windows August 28 2024 to August 28 2025 and August 28 2025 to August 28 2026. https://www.gsmls.com
John Mangini
Broker / Owner, NextHome Premier
Warren Township resident and full time broker, licensed in New Jersey since 2002. Warren, Local. is written from live Garden State MLS data, township records and primary sources. Every figure is traceable to a source listed above.